
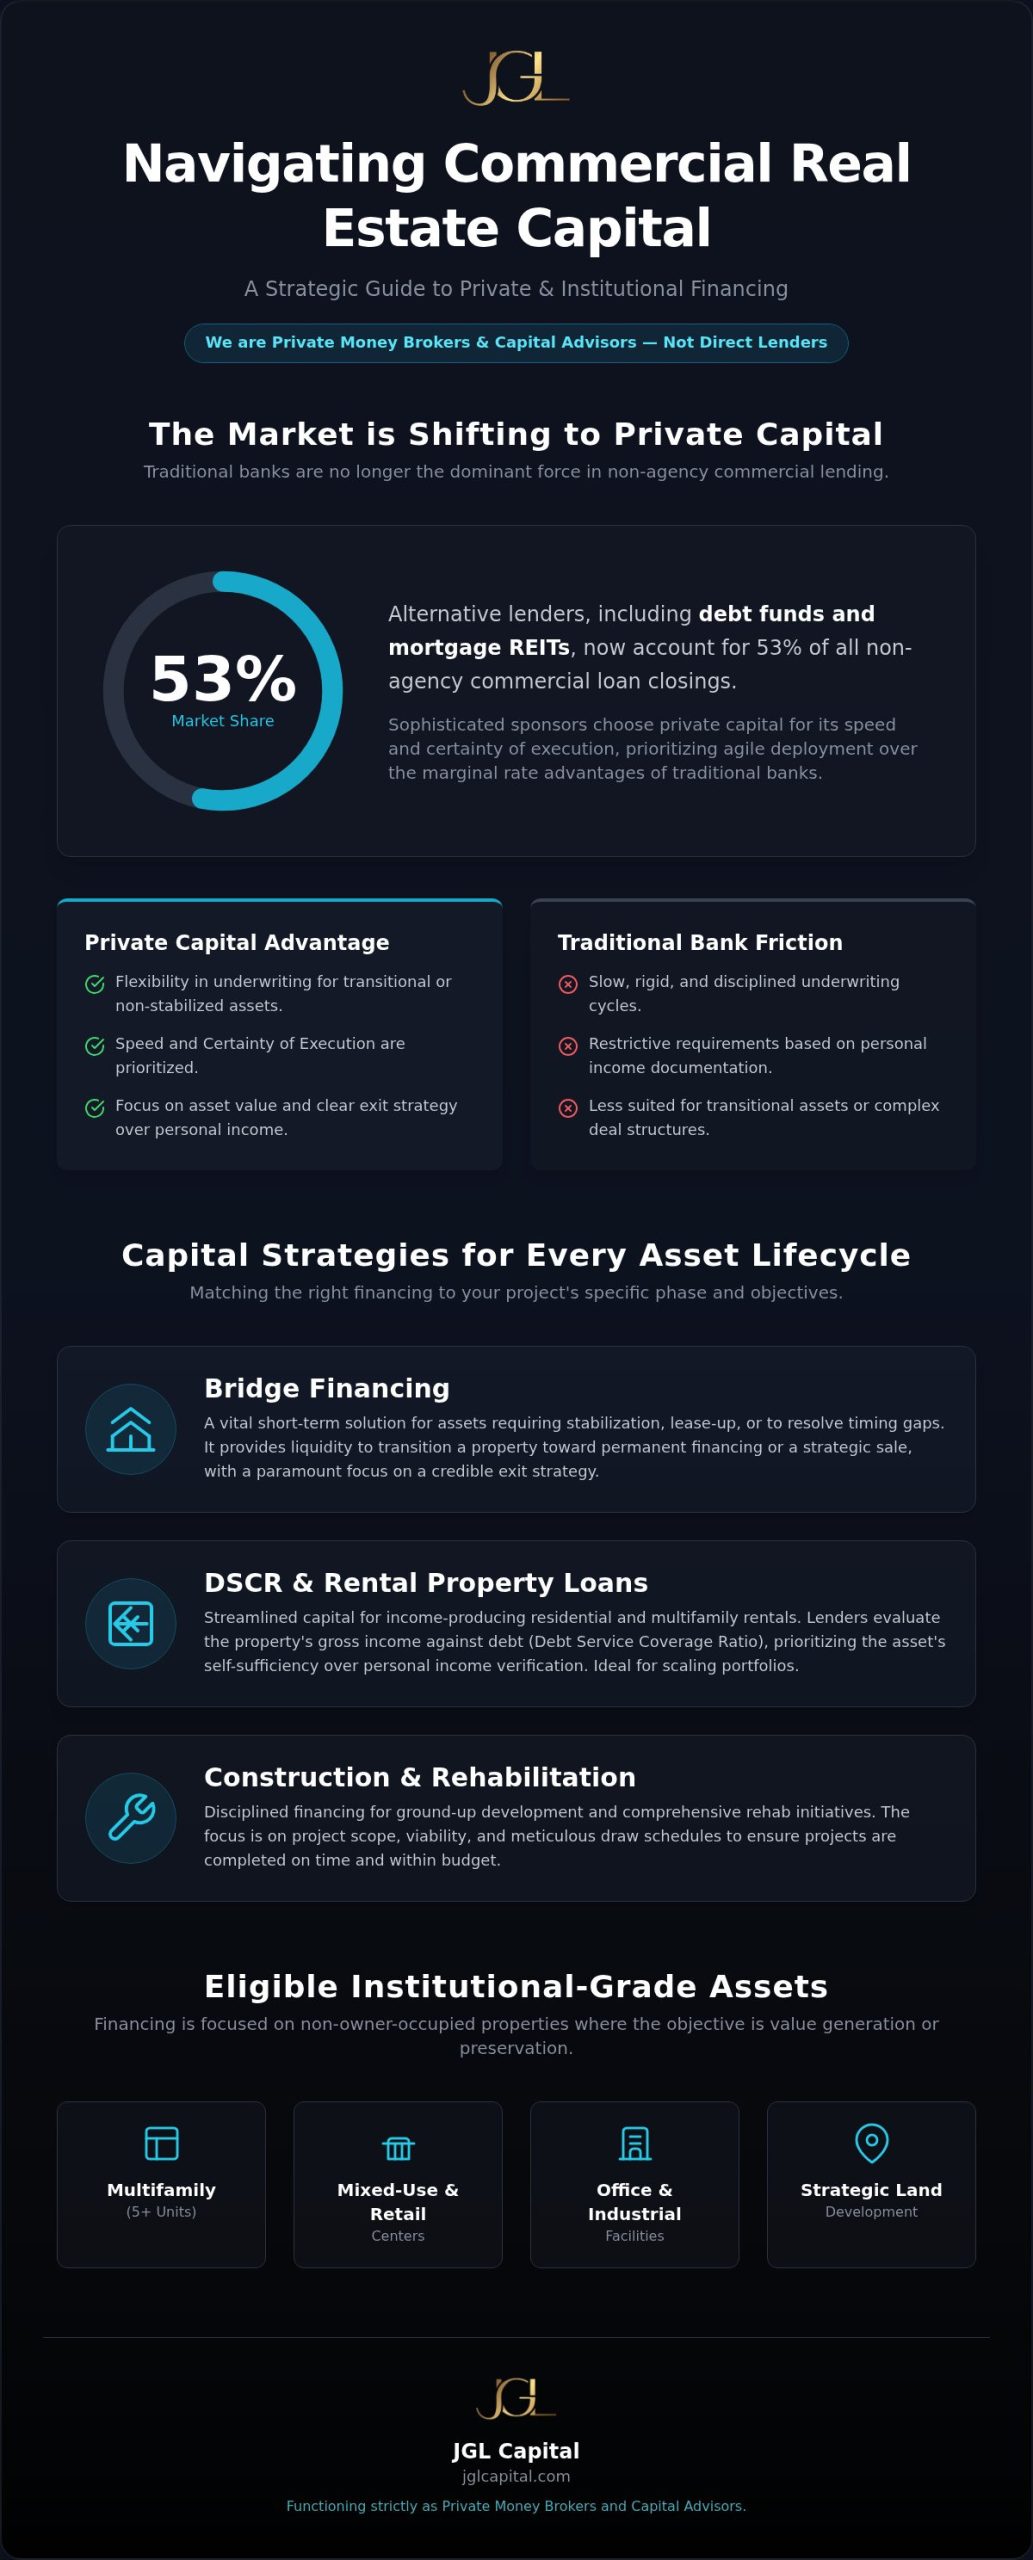
Did you know that alternative lenders, including debt funds and mortgage REITs, now account for 53 percent of all non-agency commercial loan closings? This significant market share reflects a broader transition toward private capital as traditional banks maintain disciplined, often restrictive, underwriting standards. If you’ve encountered the friction of slow approval cycles or rigid income requirements while seeking commercial real estate loans, you’re certainly not alone in your search for more responsive solutions.
It’s a reality that financing transitional or non-stabilized assets requires a partner who values intellectual capital over simple credit scores. This guide will help you navigate the complexities of modern capital allocation by identifying professional private and institutional sources that align with your specific objectives. We’ll analyze the critical trade-offs between different structures, ensuring your funding is inextricably linked to a clear exit strategy for the long-term preservation of value.
Key Takeaways
- Distinguish between traditional depository lending and the strategic flexibility of private capital to ensure your commercial real estate loans align with the specific lifecycle of your asset.
- Evaluate the utility of bridge and DSCR financing to manage timing gaps or capitalize on the cash flow of non-owner-occupied multifamily properties.
- Learn how the Initial Fit Review process functions as a vital safeguard, protecting your professional credibility by identifying deal gaps before market submission.
- Identify the core components of a disciplined deal package, emphasizing exit visibility and transparency to facilitate a successful strategic alliance with capital partners.
Understanding Commercial Real Estate Loans for Business-Purpose Transactions
A Commercial mortgage represents a sophisticated allocation of capital secured by the underlying value and income potential of a business-purpose asset. Within this framework, the primary focus remains on non-owner-occupied properties where the strategic objective is the generation or preservation of worth. JGL Capital serves as a dedicated partner in this process. It’s essential to clarify that we function strictly as private money brokers and capital advisors rather than direct lenders. This distinction ensures we maintain an objective perspective while identifying the most suitable private or institutional capital sources for your specific requirements.
Eligible Property Types and Business Purposes
The scope of business-purpose financing encompasses a diverse array of institutional-grade assets. Eligible property types typically include:
- Multifamily complexes containing five or more units
- Mixed-use developments and retail centers
- Professional office spaces and industrial facilities
- Strategic land development projects
These commercial real estate loans facilitate various transaction structures, including acquisitions, cash-out refinances, and comprehensive rehabilitation initiatives. By focusing on the asset’s lifecycle, we ensure the financing structure supports the project’s long-term viability. Investors in this space prioritize asset value and a disciplined exit strategy over exhaustive personal income documentation, allowing for more agile capital deployment in transitional deals.
The Shift Toward Private Capital in 2026
Current market data indicates that alternative lenders, including debt funds and mortgage REITs, now account for 53 percent of non-agency loan closings. This trend underscores a growing preference for the flexibility inherent in private capital. Sophisticated sponsors often find that the certainty of execution and speed provided by private sources outweigh the marginal interest rate advantages of traditional depository institutions. As banks maintain rigid underwriting cycles, the ability to secure funding aligned with a specific project timeline becomes the decisive factor in successful capital allocation.
Evaluating Capital Strategies: Bridge, DSCR, and Construction Financing
Successful capital allocation requires a nuanced understanding of the available Types of Commercial Real Estate Loans. Each financial structure serves a distinct phase of the asset lifecycle, from initial acquisition through stabilization. It’s critical to understand that while JGL Capital facilitates access to these markets, each lender independently determines underwriting requirements, rates, and terms based on the specific risk profile of the transaction. Our role as brokers is to ensure your project is positioned to meet these diverse institutional standards.
The Nuance of DSCR and Rental Property Loans
For income-producing residential and multifamily rentals, commercial real estate loans utilizing Debt Service Coverage Ratio (DSCR) metrics offer a streamlined path to capital. Lenders evaluate the property’s gross income relative to its debt obligations, prioritizing the asset’s self-sufficiency. This makes DSCR loans an effective tool for buy-and-hold landlords seeking to scale portfolios without the constraints of personal income verification. These programs focus on the property’s ability to generate sufficient cash flow to cover debt service, insurance, and taxes.
Bridge to Permanent: Planning the Long-Term Exit
Bridge financing serves as a vital short-term solution for assets requiring stabilization, lease-up, or the resolution of timing gaps. These facilities provide the necessary liquidity to transition a property toward permanent financing or a strategic sale. Aligning short-term capital with a credible refinance or sale path is paramount for the preservation of equity. For deeper context on managing transitional assets, we recommend reviewing our strategic guide on bridge loans. Ground-up development projects similarly require disciplined new construction financing, where the focus shifts toward project scope and meticulous draw schedules. JGL Capital provides the strategic guidance needed to navigate these diverse capital stacks effectively.
The Strategic Advantage of a Private Money Broker
Many investors mistakenly view the broker role as a transactional intermediary, yet in the context of sophisticated commercial real estate loans, this position is more accurately defined as a strategic capital advisor. JGL Capital functions strictly as a private money broker and capital advisor, not a direct lender; we act as a disciplined steward of your professional reputation. By leveraging over 40 years of industry experience, we ensure your request is presented with the analytical rigor required to instill confidence in capital partners. Our Initial Fit Review process identifies potential deal gaps with precision, ensuring a project is viable before it enters a lender’s pipeline.
Protecting Your Credibility with Lenders
Uncoordinated submissions to multiple institutions often lead to information fragmentation and a perceived lack of sponsor discipline. When a request appears in several pipelines simultaneously without a cohesive narrative, it can signal a lack of project clarity. Our role involves organizing and distilling complex data into a professional financing request that maximizes appeal to a nationwide network of private and institutional sources. We don’t believe in one-size-fits-all submissions. Instead, we align your specific business plan with the unique appetite of the most appropriate capital partners to ensure certainty of execution.
Navigating Non-Traditional Situations
Traditional depository institutions often struggle with transitional assets or sponsors who fall outside rigid credit boxes. An advisor provides the necessary perspective to bridge this gap, particularly when properties require stabilization or a more flexible capital structure. In such instances, hard money lenders represent a critical component of the alternative capital landscape, offering the speed and asset-based focus required for complex execution. To secure funding that reflects the true worth of your asset, engage with our private money broker services to build a lasting strategic alliance.
Preparing Your Commercial Loan Request for Optimal Execution
Securing optimal execution for commercial real estate loans demands a disciplined presentation that reflects the institutional quality of the underlying asset. Capital partners require absolute transparency regarding liquidity, interest reserves, and carrying costs to mitigate risk during the hold period. We employ a rigorous Borrower Readiness Checklist to ensure every critical decision factor is addressed prior to any market submission. This methodical preparation minimizes friction during the formal underwriting phase and protects the sponsor’s professional standing among elite capital sources.
The Essential Deal Summary
A well-structured deal summary serves as the primary instrument for determining program fit. This package must be concise yet comprehensive, providing the purchase price, current valuation, and a detailed use of funds alongside a professional borrower resume. However, the most critical component is a well-supported exit strategy. Private capital sources prioritize the visibility of their principal’s return, whether through a strategic refinance or a planned asset disposition. Without a credible path to liquidity, even the most robust assets may struggle to secure favorable terms in the current market.
Next Steps in the Financing Process
Following a successful initial review of your project’s fundamentals, we facilitate the issuance of a term sheet. It’s vital to recognize that a term sheet provides a summary of proposed terms, which remain subject to exhaustive underwriting and final credit approval. This stage represents the transition from strategic alignment to operational delivery. We invite you to discuss your new construction project or stabilized commercial asset with a JGL advisor to ensure your capital allocation remains efficient and purposeful. By submitting a concise deal summary for our review, you take the first step toward a strategic alliance that values the long-term preservation of equity.
Securing Your Strategic Alliance for Long-Term Value
Navigating the complexities of the current financial landscape requires more than just searching for the lowest rate. It demands a disciplined alignment between your asset’s lifecycle and the specific appetite of capital sources. By prioritizing exit visibility and professional deal packaging, you ensure your commercial real estate loans are structured for stability rather than just immediate liquidity. This strategic approach is essential for preserving equity in transitional assets where traditional banks often fall short.
With over 40 years of industry experience, John E. Litton provides the seasoned guidance necessary to evaluate trade-offs and risks with absolute transparency. As a nationwide private money broker, JGL Capital offers access to an extensive network of lenders while functioning as a dedicated capital advisor for your business-purpose transactions. Submit your project for an initial financing-fit review with JGL Capital to align your objectives with the right capital stack. You don’t have to navigate these hurdles alone; a disciplined partner makes all the difference in building a lasting legacy.
Frequently Asked Questions
What is the difference between a private money broker and a direct lender?
A direct lender provides capital from its own balance sheet, whereas a private money broker, like JGL Capital, acts as a strategic advisor to identify appropriate financing sources. We don’t lend our own funds or make final underwriting decisions. Instead, we leverage a nationwide network of private and institutional lenders to match your business-purpose transaction with the most suitable program. This model provides access to diverse capital structures rather than a single lender’s limited appetite.
Does JGL Capital finance owner-occupied residential properties?
No, JGL Capital doesn’t arrange financing for owner-occupied residential properties or consumer mortgages. Our services are strictly dedicated to business-purpose transactions, including commercial real estate loans, multifamily projects, and investment rentals. We focus on non-owner-occupied assets where the primary objective is the creation or preservation of value. This specialization ensures our strategic guidance remains centered on the unique requirements of professional real estate investors and developers across the country.
How does a bridge loan exit strategy impact approval odds?
A credible exit strategy is often the most critical element of a private money request, significantly influencing the lender’s final approval decision. Lenders prioritize the visibility of their principal’s return, whether through a strategic refinance or the planned sale of the asset. Without a well-supported path to liquidity, even robust properties may face difficulty. We stress-test these exit assumptions during our initial review to ensure the capital stack aligns with your project’s long-term timeline.
What documentation is typically required for a commercial real estate loan request?
While requirements vary by lender and program, a standard commercial real estate loan request typically requires a concise deal summary. This package should include a property description, a detailed use of funds, and a professional borrower resume highlighting relevant experience. Additionally, you’ll need to provide evidence of liquidity for reserves and carrying costs. For DSCR programs, current leases and income statements are essential to demonstrate the property’s ability to cover its debt obligations.
Why should I use a broker instead of contacting lenders directly?
Using a broker allows you to frame your request professionally and access a broad network of capital sources through a single point of contact. Rather than managing fragmented communications with individual institutions, you benefit from our 40 years of industry experience in identifying the right program fit. We protect your credibility by coordinating submissions and comparing available structures. This strategic alliance ensures you aren’t limited by one bank’s balance sheet or rigid credit box.