
A property’s rent roll is not its net operating income. A net operating income (NOI) calculation starts with rental and other property income, accounts for vacancy and credit losses, then subtracts operating expenses. The result measures income from the property’s operations before financing and owner-level costs.
That distinction matters: a property may generate substantial rent but produce a very different NOI after accounting for empty units, unpaid rent, maintenance, taxes, insurance, utilities, and management costs. Vacancy losses reduce the rent the property can reasonably expect to collect, so relying on potential rent alone can overstate operating performance.
This article explains what NOI measures, which income and expenses belong in the calculation, and how vacancy affects the result. It also clarifies why mortgage payments, income taxes, depreciation, and major capital projects are generally excluded from property-level NOI, even though they can still affect an owner’s overall cash flow. Understanding these distinctions helps you interpret the figure more accurately when assessing a property’s operating performance.
Key Takeaways
- Separate a property’s operating performance from financing and owner-level costs to interpret its income more clearly.
- Include property-generated revenue such as parking, laundry, storage, and pet fees when assessing total income.
- Use historical records or comparable properties to estimate vacancy and credit losses rather than relying on full occupancy.
- Compare income and expenses over a consistent period so the resulting figure provides a meaningful basis for evaluating the property.
What is Net Operating Income?
Net operating income measures property revenue remaining after direct operating expenses are deducted. A net operating income (NOI) calculation focuses on the asset’s operations, not its financing or the owner’s broader financial position.
Operating Income and Expenses
Operating income is the revenue a property generates, less the costs required to operate it. This distinction helps investors assess performance before mortgage payments or owner-level taxes affect the result.
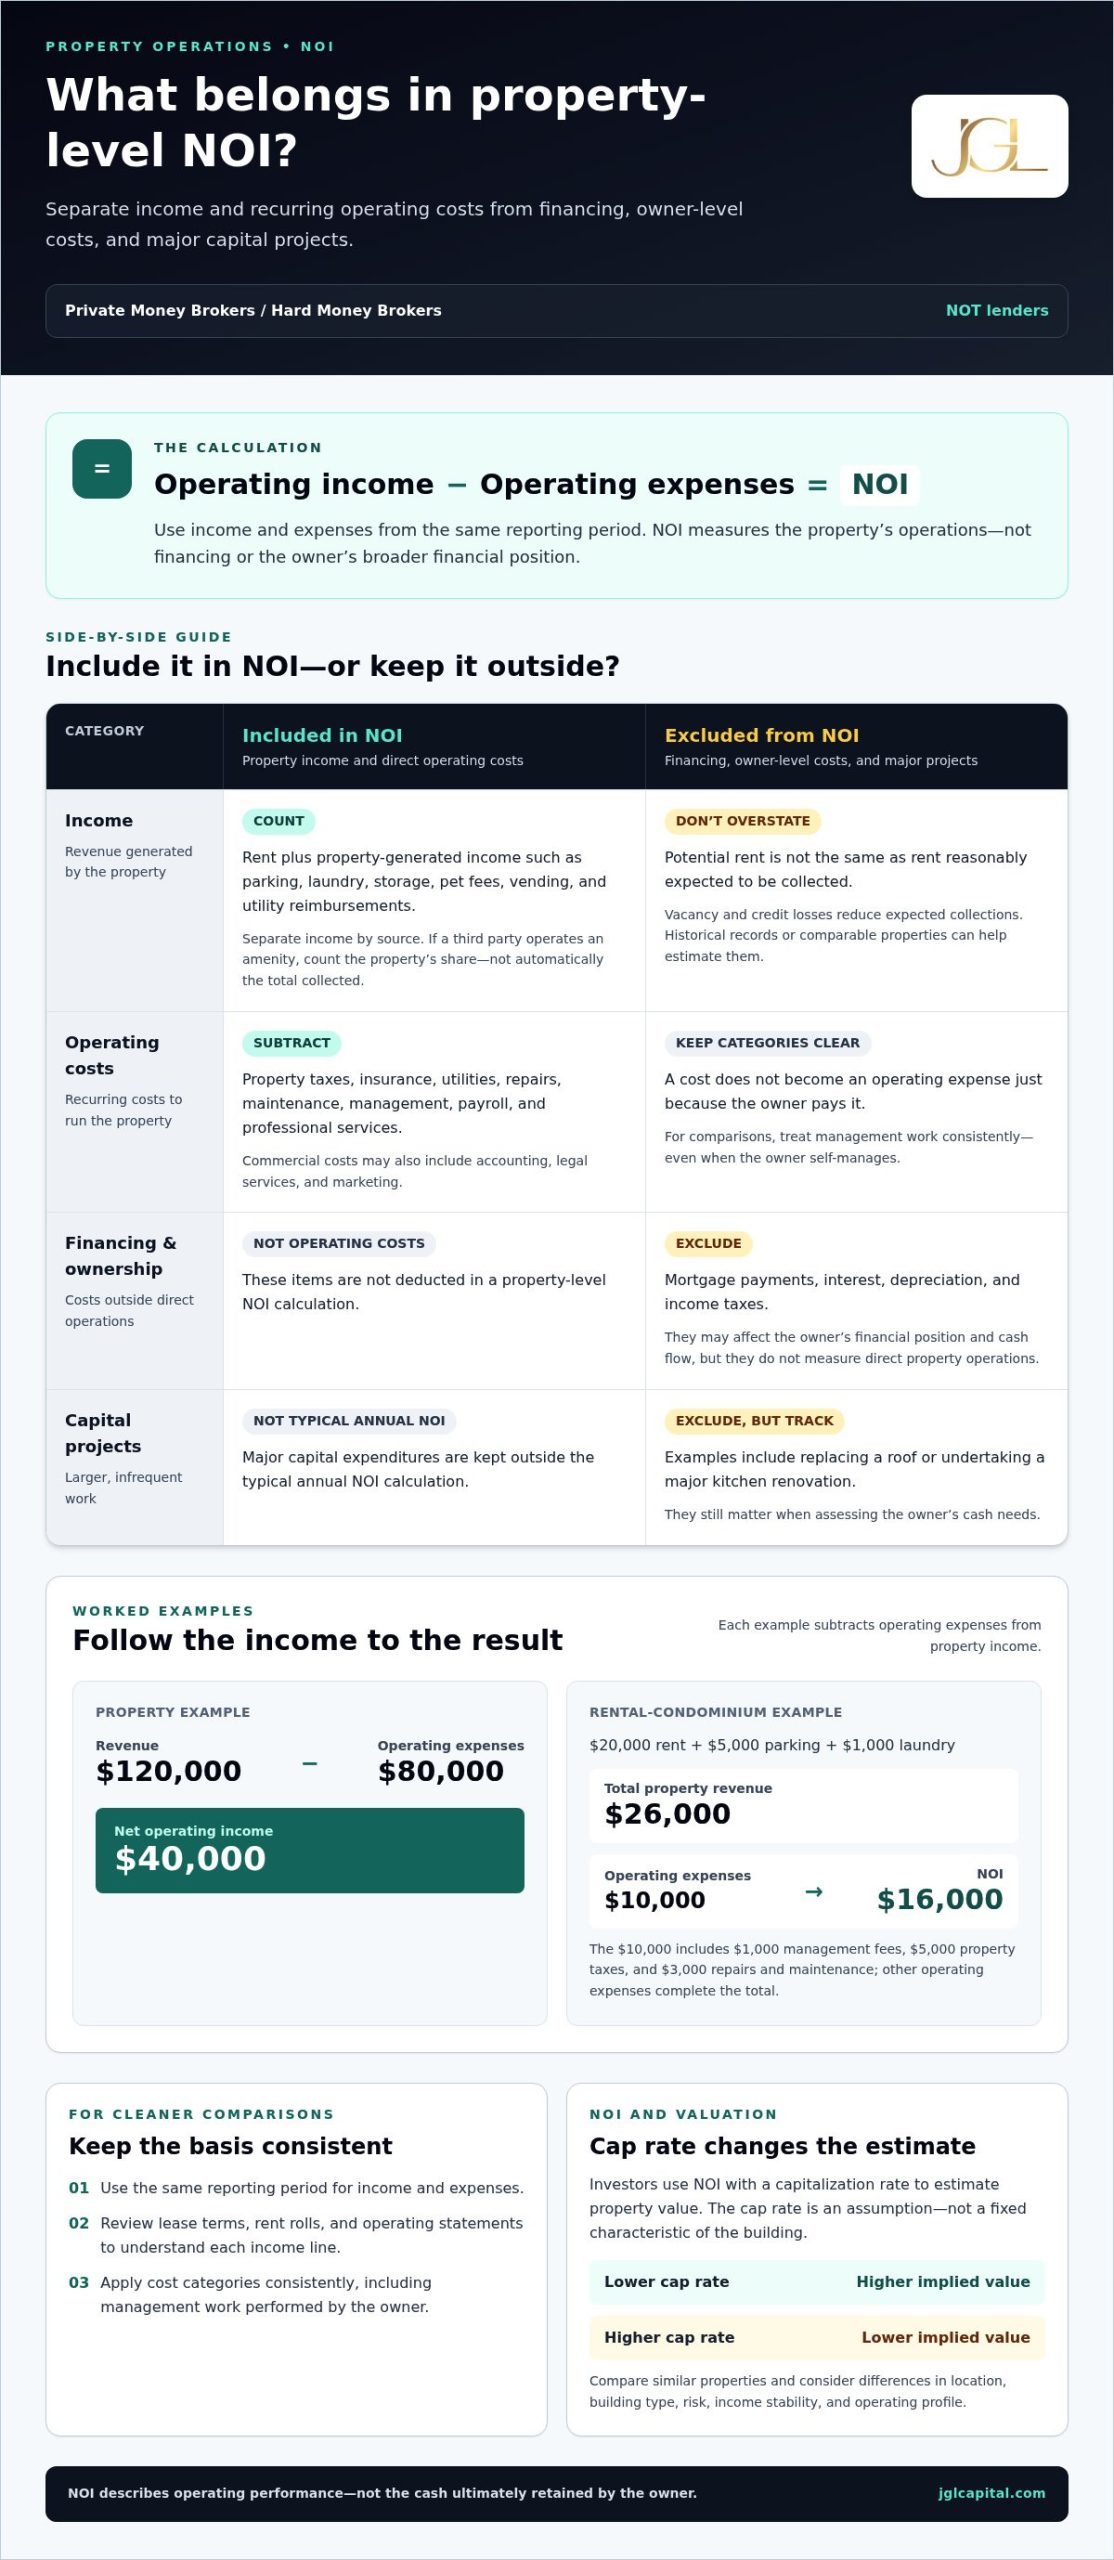
For example, a property with $120,000 in revenue and $80,000 in operating expenses produces $40,000 in NOI. The expenses can include real estate taxes, insurance, utilities, repairs, maintenance, management, payroll, and professional services. Reviewing each expense helps determine whether the property’s income reflects its operating performance, rather than costs tied to financing or ownership.
Commercial Property Operating Costs
Commercial property operating expenses are recurring costs of maintaining the building and its operations. They may include property management, repairs, insurance, real estate taxes, utilities, accounting, legal services, and marketing.
The precise expense mix depends on the property and its operating arrangements. For example, a commercial building with shared areas may require regular maintenance, while a managed property may incur management fees. Categorizing costs consistently gives investors a clearer basis for comparing performance and evaluating a real estate investment. A lender may also consider NOI when assessing a property’s capacity to support its obligations.
Expenses Excluded From NOI
NOI excludes costs that do not represent ordinary property operations, including mortgage payments, interest, depreciation, income taxes, and capital expenditures. These items may affect an owner’s financial position, but they do not measure the property’s direct operating performance.
Capital expenditures are larger, infrequent projects, such as replacing a roof or undertaking a major kitchen renovation. They are excluded from typical annual NOI, although owners still need to account for them when assessing cash needs. Debt service, capital expenditures, and income taxes affect after-tax cash flow. Keeping these measures distinct helps investors assess operating results without mistaking NOI for the cash ultimately retained by the owner.
Additional property income
Ancillary revenue can reveal how a property’s income depends on more than its primary leases. Parking, laundry, storage, pet fees, vending machines, and utility reimbursements may all contribute, but their reliability can differ. For example, parking tied to tenant leases has a different basis from occasional visitor payments. Separating income by source helps show which revenue is recurring and which may vary with use or occupancy.
Records matter. Compare lease terms, rent rolls, and operating statements to understand how each income line is generated and recorded. If a third party operates an amenity, distinguish the property’s share from the total amount collected. This helps prevent gross receipts from overstating revenue attributable to the asset.
NOI as a Valuation Metric
Investors use NOI with a capitalization rate to estimate property value, but the result depends on the rate selected. A lower cap rate produces a higher implied value for the same NOI; a higher rate produces a lower one. The cap rate is an important assumption, not a fixed characteristic of the building.
For a sound comparison, assess similar properties and consider differences in location, building type, and operating profile. If two assets have similar NOI but different risk or income stability, applying the same cap rate may obscure those distinctions. Treat the valuation as an analytical estimate, not a standalone measure of worth.
Management Fees and Comparisons
Self-management can make a property’s reported expenses look different from those of a professionally managed asset. For a useful comparison, account for management work consistently, even when the owner performs it personally. Otherwise, an apparent operating advantage may reflect bookkeeping rather than a difference in the property itself.
Review income sources and cost treatment together before using NOI to compare investment properties. If you’re considering financing for an income-producing asset, explore commercial real estate loan options as part of evaluating the transaction.
NOI formula
The net operating income (NOI) calculation subtracts a property’s operating expenses from its operating income. Add rental revenue and other property-generated income, then deduct expenses directly tied to operations. Use the same reporting period for income and expenses so the resulting figure has a clear meaning.
NOI = operating income − operating expenses
For this formula, operating income includes rent and property-generated revenue, such as parking or laundry income. Operating expenses are the recurring costs of running the property. Financing is excluded, allowing investors to compare operating performance without mixing property expenses with loan terms.
A rental-condominium example shows how the figures come together. Rental income of $20,000, parking fees of $5,000, and laundry revenue of $1,000 produce total revenue of $26,000. Subtracting $10,000 in operating expenses gives NOI of $16,000. The calculation works because each income source and qualifying expense is accounted for once, within the same period.
The $10,000 expense total includes property-management fees, property taxes, and repairs and maintenance. In this example, those items are $1,000, $5,000, and $3,000 respectively; the remaining operating expenses complete the stated total. Clear categories make it easier to review how each cost affects the final figure and to compare the calculation with property records.
Mortgage payments, interest, income taxes, depreciation, and capital expenditures do not belong in this operating formula. They still affect an owner’s cash position, but they describe financing, tax treatment, or major projects rather than ordinary property operations. Keep them separate when reviewing NOI.
NOI can also inform a capitalization rate analysis. The cap rate divides NOI by purchase price, while estimated property value can be derived by dividing NOI by a relevant cap rate. These measures use the same operating figure for different purposes: one expresses income relative to price, while the other indicates implied value.
Gross operating income and vacancy losses
Potential rent assumes every unit is occupied and paying. Gross operating income reflects vacancy and credit losses, giving investors a more grounded view of the revenue a property can be expected to generate.
Gross Operating Income
Gross operating income measures property revenue after vacancy and credit losses, with additional property income included. It helps distinguish scheduled rent from income the property can reasonably generate under its occupancy conditions.
Parking or laundry revenue can add to that amount. Gross operating income captures these occupancy effects, making it a useful starting point for assessing a property’s income potential.
Vacancy Losses and Costs
Vacancy loss is rental income forgone while a unit is unoccupied; credit loss reflects rent owed but not collected. Both reduce the revenue attributable to a property during the reporting period.
Investors can also consider vacancy rates at comparable properties when estimating expected losses. The most useful comparison involves similar buildings and operating conditions, rather than assuming every unit will remain occupied. Tenant turnover can affect collected rent even when a unit is later leased, so annual records may reveal patterns that a single rent roll does not show.
Revenue and Effective Gross Revenue
Effective gross revenue starts with potential rent, subtracts vacancy and credit losses, then adds other property income. This adjusted measure accounts for occupancy and revenue beyond lease payments.
The resulting amount reflects operating revenue before expenses. Compare it with NOI, which also accounts for operating expenses. This distinction helps clarify whether a change in profitability comes from occupancy, other revenue, or costs.
For a rental-property financing discussion, discuss rental property financing in light of the property’s income profile.
JGL Capital: New Construction Loans
JGL Capital LLC is a private money broker, not a lender, and helps borrowers explore New Construction Loans for real estate projects. If you’re evaluating a planned development, the NOI principles in this guide can help frame expected property income and operating costs once the asset is operating. Projected figures are not the same as an established operating history, so keep assumptions about rent, occupancy, and expenses distinct from actual results.
Consider speaking with JGL Capital LLC about private money options for a new construction project. As a broker, JGL Capital LLC can help connect the financing discussion to the project’s objectives and property fundamentals. Contact JGL Capital LLC to discuss your project.
Put the Numbers in Context
Use a property’s NOI as one input in a broader investment review, alongside its condition, business plan, and financing structure. Before relying on projections, consider how changes in rent, occupancy, or operating costs could alter the property’s performance. A net operating income (NOI) calculation is most useful when its underlying assumptions are clear and relevant to the decision.
For a development or acquisition, distinguish projected figures from actual operating results and keep assumptions visible as plans evolve. If financing is part of your next step, JGL Capital can help you explore possible private-capital sources for a business-purpose real estate transaction.
Contact JGL Capital to discuss your project. A thoughtful review can help you approach the next decision with greater clarity.
Frequently Asked Questions
Why is NOI important in real estate?
NOI helps investors assess a property’s operating performance independently of its financing structure. It also informs valuation measures and lender analyses, including debt yield and debt service coverage. For a useful comparison, review properties with similar uses and accounting periods. A change in NOI can affect an asset’s indicated value and financing metrics, so consistent income and expense assumptions matter when evaluating a purchase or existing portfolio.
How is NOI Calculated?
Subtract operating expenses from property operating income after accounting for vacancy and credit losses. A net operating income (NOI) calculation begins with potential rent, deducts expected losses, adds other property-generated income, and then subtracts ordinary operating expenses. Keep financing payments, owner income taxes, and capital projects separate. For a reliable result, use income and expenses from the same period and avoid mixing actual figures with unsupported estimates.
What are the Biggest Drivers of NOI?
Rental income, occupancy, additional property revenue, and operating costs are the principal drivers of NOI. Changes in lease terms or a vacant unit affect collected income; rising insurance, utilities, or maintenance costs reduce what remains. Some factors, such as tenant demand, depend on the market, while property management may influence expense controls. Review both sides of the calculation to understand what is driving a change.
What is a Good NOI Margin?
There is no single NOI margin that defines a strong property across every market and asset type. NOI margin is NOI expressed as a share of operating revenue, showing how much revenue remains after operating expenses. Compare properties with similar uses, locations, occupancy patterns, and expense treatment. A margin can appear stronger simply because certain costs were classified differently, so consistent accounting is essential.
What is a Good NOI for a Rental Property?
A good NOI depends on a rental property’s purchase price, condition, location, income stability, and operating costs. An absolute dollar figure alone cannot show whether a property is performing well. Compare its NOI with similar rentals and consider how the result relates to the investment price and expected obligations. A small property and a larger apartment building can produce very different NOI figures without that difference indicating which is the stronger investment.
What is the Operating Expense Ratio?
The operating expense ratio measures operating expenses against operating revenue, commonly expressed as a percentage. Divide qualifying expenses by revenue for the same period. The ratio rises when operating costs take a larger share of collected income. Investors use it alongside NOI to examine cost control, but comparisons are meaningful only when properties use consistent expense categories and revenue assumptions.